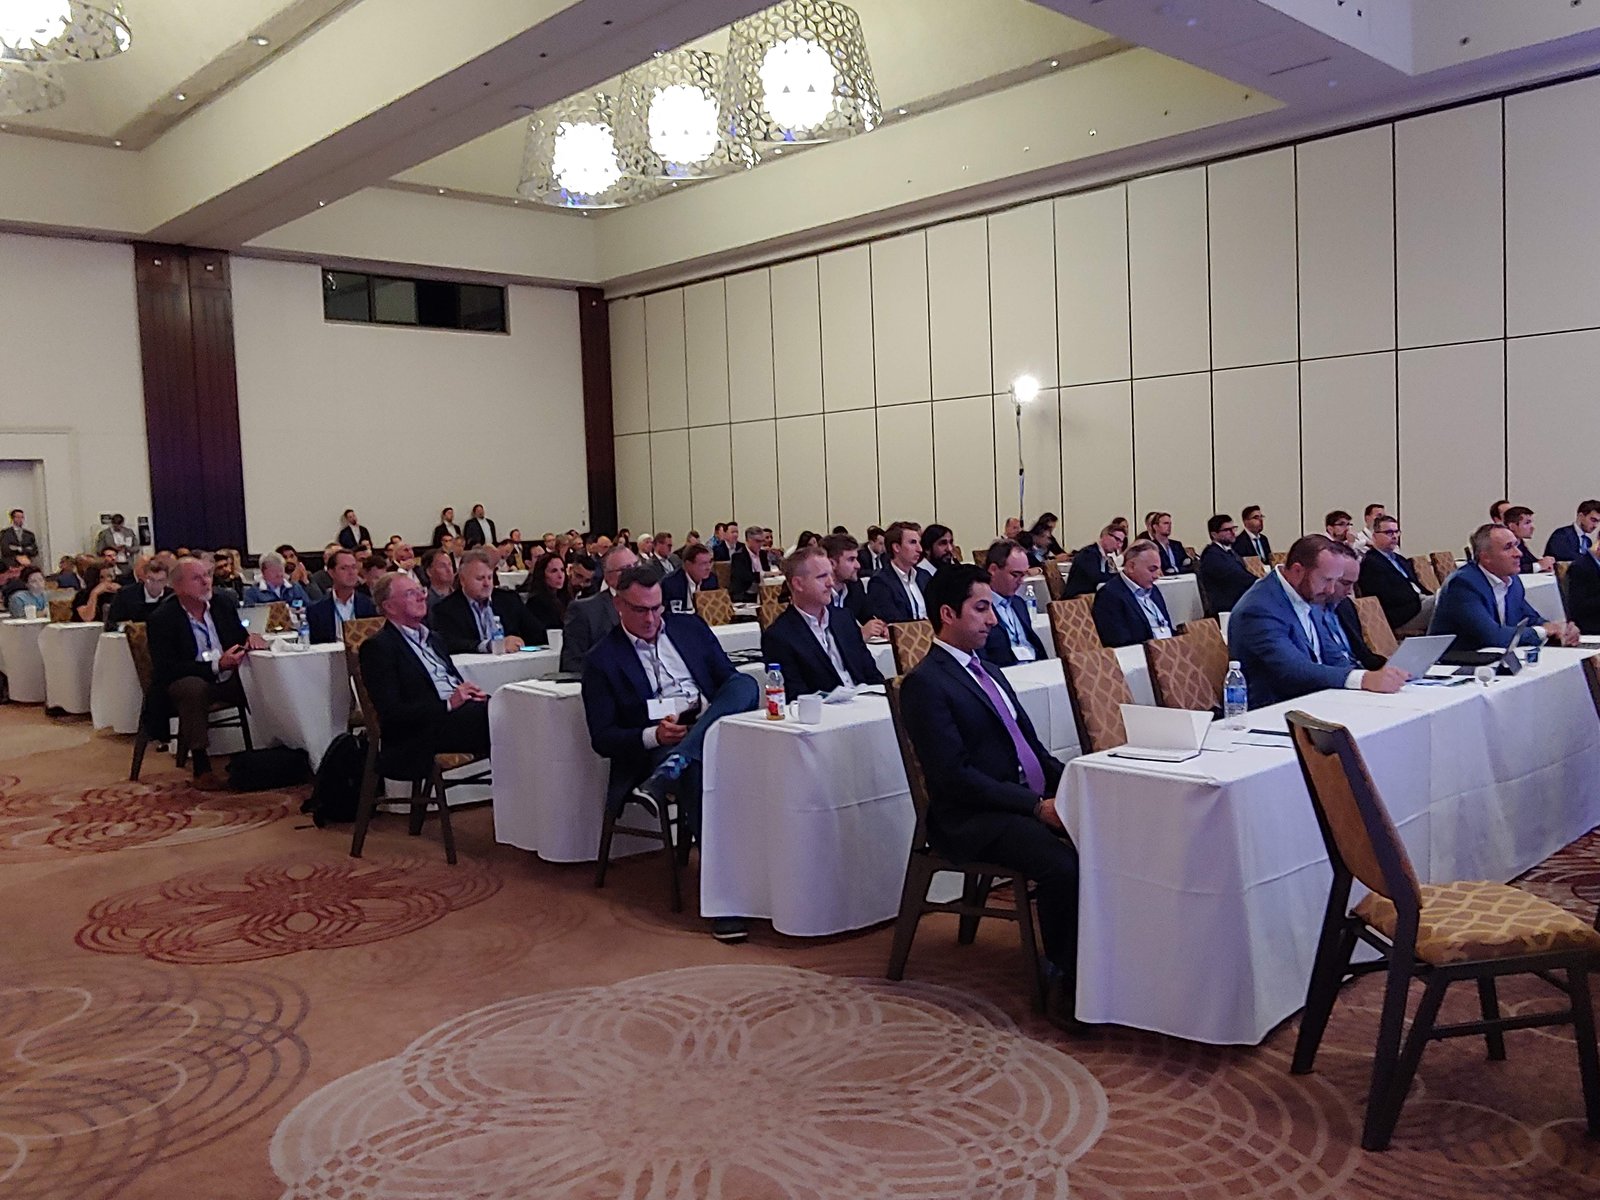
Choosing investor conferences
The meeting book matters more than the name on the program
Most companies choose conferences by reputation. The better test is the meeting book: which funds attended last year, how many one-on-ones a company of your size received, and whether those investors can own a stock like yours. Ask the organizer for both before committing management's time.
The host matters. A conference run by a bank that publishes research on your sector, and covers you or wants to, comes with a sales desk that has already primed its accounts. A large-cap headliner where you are the smallest company in the building rarely delivers the same meetings, however strong the brand. Sector and retail investor shows have their place, particularly for companies building a retail following, but they should pass the same test.
Frequency has a ceiling. For most management teams, one or two conferences a quarter is the practical limit. Past that, the time comes out of running the business, and investors notice.
Match the conference to the shareholder base you want, not the one you have. A growth story spends a day in front of value funds for little return.
Pair it with a roadshow. When management travels to a conference city, add a day of non-deal meetings: existing holders first, then the funds you want, then local analysts and bankers. The conference justifies the trip; the roadshow day often produces the better meetings.